How to Pay for Medical Treatment in China
How to pay hospital bills in China with cards, mobile wallets, e-CNY, and cash explained.
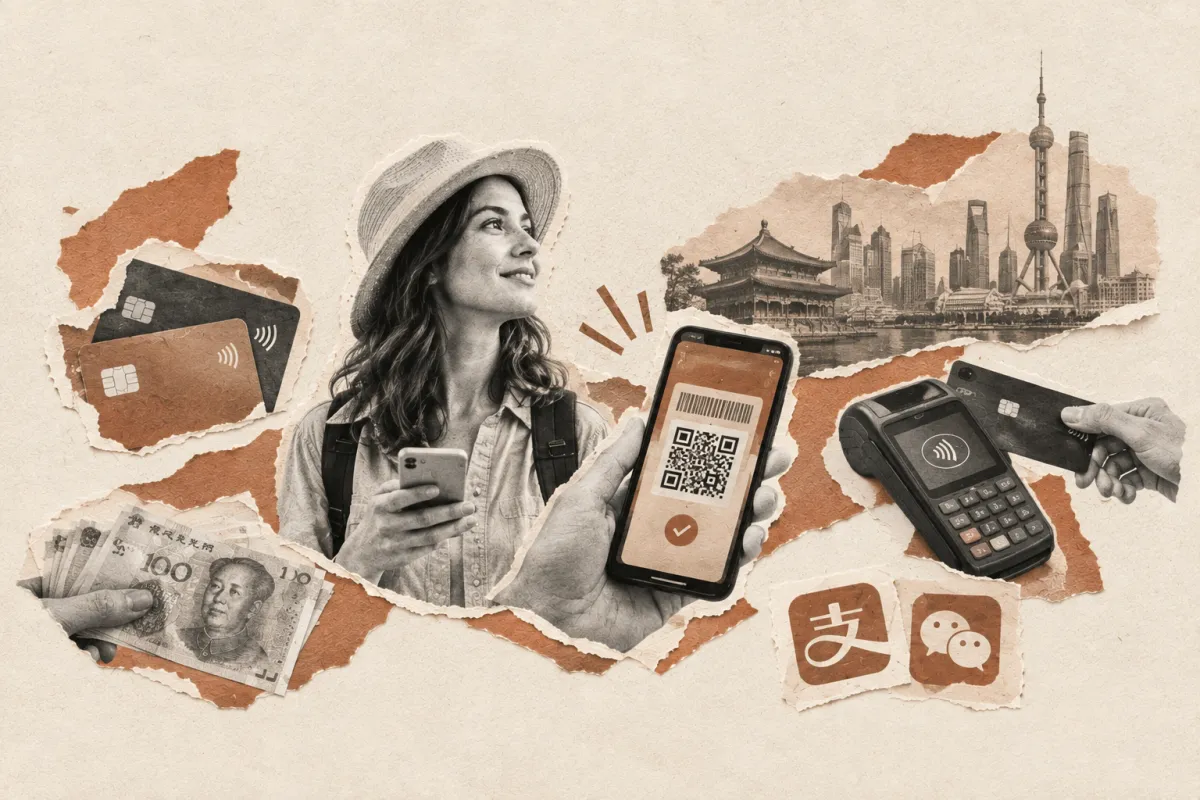
Before traveling to China for medical care, many international patients worry less about the procedure itself than about a very practical question: how, exactly, do I use my money in China?
From a taxi fare to an admission deposit worth thousands of dollars, payment habits in China differ from those in many other countries. The good news is that, by 2026, China operates a well-established framework often summarized as "cards for large amounts, QR payment for small amounts, and cash as the universal fallback." In February 2026, Chinese authorities issued the Opinions on Improving the Convenience of Digital Services for Overseas Visitors, which explicitly names medical care among the key areas whose digital-service bottlenecks should be removed by 2027.
This guide is built around the payment situations you will actually encounter across a medical journey. It explains six payment methods, their fees and limits, and how to handle large hospital bills.
1. The Big Picture: Six Tools, Each with a Role
| Payment method | Best for medical/daily use | Chinese bank card needed? | Key limitation |
|---|---|---|---|
| Overseas physical card (Visa, Mastercard, Amex, JCB, Discover, Diners Club, UnionPay) | International hospitals/departments, large charges, ATM withdrawal | No | Not accepted at small merchants or ordinary local billing windows |
| Alipay / WeChat Pay linked to an overseas card | Daily spending, food, transport, hospital mini-programs | No | 3% fee above RMB 200; per-transaction and annual limits |
| Home e-wallet (inbound "home-wallet" interconnection) | Offline QR payment with zero setup for short-stay visitors | No (no Chinese app needed) | Only connected wallets; offline only, not for most online/mini-program use |
| Digital RMB (e-CNY) | Offline emergencies, tap-to-pay hardware cards, departure tax refund | No | Acceptance still expanding; keep a backup outside major cities |
| RMB cash | Universal fallback, including large payments | No | Carrying, counting and security costs |
| Domestic bank account | Long-term residents and treatment; removes limits | Yes (residence/work documents) | Unnecessary and harder for short-stay visitors |
The key is to combine tools, rather than relying on a single method for everything.
2. The Six Methods in Detail
2.1 Overseas physical cards: the baseline for large medical expenses
Carrying an overseas-issued Visa, Mastercard, American Express, JCB, Discover, Diners Club or UnionPay card is the safest baseline. It provides two core functions:
• POS payment: Widely accepted at airports, international hotels, A-level scenic spots, major business districts, foreign-oriented exhibition venues and departure tax-refund stores. Large hospitals with an international medical department typically accept overseas cards at designated billing windows.
• ATM withdrawal: You can withdraw RMB cash (ATMs dispense only RMB) from machines displaying the relevant card-network logo. Withdrawal fees are set by your overseas issuing bank.
Note that community hospitals, small clinics and street-level individual merchants generally do not accept overseas cards. Treat your card as the tool for large, foreign-oriented expenses, and use mobile payment for daily small purchases. Before treatment, confirm with the hospital's international department whether its billing counters accept your specific card.
2.2 Alipay / WeChat Pay linked to an overseas card: the daily-workhorse method
This is the most convenient option for most international patients and requires no Chinese bank account. Register with an overseas phone number, complete real-name verification with your entry document, bind an overseas credit or debit card, and you can pay by QR code at restaurants, for transport and retail, and within many hospital mini-programs and self-service kiosks. WeChat Pay currently accepts seven international card networks — Visa, Mastercard, American Express, Discover, Diners Club, JCB and UnionPay International; Alipay accepts a slightly shorter list (Visa, Mastercard, JCB, Diners Club and Discover). The in-app card-selection screen always shows the current lineup.
Under the platforms' current official rules:
• Fee: Transactions of RMB 200 or below are free of charge. Above RMB 200, a 3% service fee applies to the entire transaction amount (not only the portion above RMB 200). If you obtain a refund, the fee is refunded proportionally.
• Limited-time fee waiver for first-time users:For users who bind an international bank card for the first time in 2026, the 3% fee is waived for 90 consecutive calendar days from the first transaction, covering up to RMB 1,000 of spending per day. Tencent has stated that this promotion runs through December 31, 2026; please confirm the current terms in the app.
• Limits — two tiers, and the stricter one applies. After passport verification, the central-bank institutional ceiling is about USD 5,000 per transaction and USD 50,000 per year. In daily practice, however, each platform's own RMB risk-control cap usually binds first: on WeChat Pay this is roughly RMB 6,000–6,500 per transaction, RMB 50,000 per month and RMB 60,000–65,000 per year; figures are revised periodically and differ slightly between platforms. Your card network and issuing bank may impose a lower channel limit. The definitive figure is always the cap shown in your in-app wallet and on the payment page.
• Functional limits: Overseas-card accounts support everyday consumption within the Chinese mainland. They generally do not support red packets or person-to-person transfers, and some public/utility payment functions are unavailable.
• A binding failure or declined transaction caused by an overseas bank's cross-border risk control is a normal compliance event; try another card or contact your issuing bank.
What this means for medical costs: registration, tests and medication costing a few hundred to a few thousand RMB are very easy to settle by QR code. Once a charge exceeds the per-transaction limit, you will need another method (see Part 3).
2.3 Home-country e-wallets: zero-setup for short-stay visitors
In 2026, China continued to expand inbound cross-border QR interconnection (the "home-wallet" or waibao neiyong model), built on a unified cross-border QR gateway developed under the guidance of the People's Bank of China. If your home e-wallet has been connected, you can pay at WeChat Pay or Alipay merchants using your familiar wallet app, without downloading a Chinese app or binding a card.
• Through WeChat Pay / TenPay Global: As of May 2026, 36 overseas wallets had gone live, including WeChat Pay HK (Hong Kong SAR), PayPal (initially for U.S.-based users), K PLUS (Thailand), NAVER Pay (Republic of Korea), Boost (Malaysia) and Bakong (Cambodia), with further wallets such as Venmo, ShopeePay, GrabPay, Maya, ZaloPay, LiquidPay and Hipay joining or signed through the unified gateway.
• Through Alipay+: Ant International's Alipay+ connects more than 40 e-wallets across over 100 markets; examples usable in mainland China include Kakao Pay (Republic of Korea), Touch 'n Go eWallet (Malaysia), TrueMoney (Thailand), GCash (Philippines) and AlipayHK.
Coverage is expanding continuously, so check whether your own wallet is supported before you travel. Note that this service primarily supports offline, in-person spending and generally does not cover Chinese online e-commerce or most mini-program transactions. (Separately, Chinese residents can use WeChat Pay to scan local QR codes when traveling abroad in countries such as the Republic of Korea, Thailand, Malaysia, Singapore and Sri Lanka; that is the reverse direction and is not the inbound service described here.)
2.4 Digital RMB (e-CNY): for no-network, no-card emergencies and departure refunds
The digital RMB is China's legal digital fiat currency. It was upgraded to version 2.0 in early 2026: balances in real-name wallets now accrue interest and are covered by deposit insurance, and the number of operating institutions has expanded to 22. Two wallet forms are available to overseas visitors:
• Software wallet (App): Register in the e-CNY app with an overseas phone number, bind an overseas bank card, top up as needed, and transfer remaining balances back to the original overseas card through a compliant closed loop.
• Hardware wallet (physical card): Available at major ports of entry and bank branches upon presentation of your passport. It requires no phone, no linked card and no network, supporting offline tap-to-pay. Examples include the "Qingdao Pass" cultural-and-tourism card at Qingdao Jiaodong Airport and Bank of China's "Mifang Card," which integrates payment, mobile data and transport (over 10,000 cards issued, covering more than 120 countries and regions). In Shenzhen, departure tax refunds can be credited instantly to a hardware-wallet balance.
Hardware wallets are especially useful immediately after arrival, when phone service or connectivity may be unreliable. Because e-CNY acceptance is still expanding, keep an alternative method for remote areas and small merchants.
2.5 RMB cash: the fallback that always works
China has built a multi-level cash-service network covering ports, business districts and urban areas. You can exchange foreign currency for RMB (and back) at bank counters, licensed exchange outlets and self-service machines, withdraw small amounts at ATMs, and handle larger exchanges at physical branches. Unused RMB cash can be converted back to foreign currency at designated port outlets before departure.
Cash carries no scenario restrictions and avoids the limits and risk-control interruptions of digital payment. Under China's rules against refusing legal tender, no institution, including a hospital, may reject RMB cash. Its trade-offs are the costs of carrying, counting and securing banknotes, so keep it mainly for emergencies and large-value backup.
2.6 A domestic bank account: the best option for long-term residents
If you hold a work-type residence permit or permanent residence status and require long-term treatment or working life in China, opening a domestic RMB settlement account and linking its debit card to mobile payment is the most complete solution. It removes cross-border service fees and transaction limits and fully supports salary, transfers, bill payment and online spending.
Short-term tourists and business visitors generally do not need, and may find it difficult to open, a full-function account. If genuinely necessary, some banks offer tiered basic accounts on presentation of a passport, subject to local branch requirements. For a medical trip of around two weeks, the combination of an overseas card, mobile payment and some cash is sufficient.
3. How to Handle Large Medical Bills (the Most Important Section)
Small outpatient charges are easy; what requires advance planning are admission deposits, surgery, and procedures such as dental implants or bone grafting that can cost tens of thousands of RMB. Such amounts may exceed mobile-payment limits or trigger overseas-bank risk controls. Arrange them in this order:
1. Confirm payment methods with the hospital's international department before departure. Ask three questions: whether your Visa/Mastercard is accepted, whether cross-border wire transfer (T/T) to the hospital's corporate account is supported, and the amount and timing of any admission deposit.
2. Prefer an overseas card or cross-border wire transfer for large amounts. Swipe your card where the international department accepts it; for very large sums, wire funds to the corporate account details provided by the hospital, and retain the remittance receipt together with the hospital invoice for insurance claims.
3. Use staged deposit payments where available.Many hospitals allow deposits to be paid in installments, which can be split across methods or calendar days so that each charge falls within per-transaction limits.
4. Keep cash as the final fallback. Billing windows may not lawfully refuse RMB cash.
5. Retain all documents. The official invoice (medical charging receipt), itemized bill, diagnosis and medical record are the core documents for commercial-insurance reimbursement and later claims.
4. Recommended Combinations by Length of Stay
• Short medical trip (1–3 weeks: checkup, dental, ophthalmology, minor procedures):one overseas credit card (card payment plus ATM fallback) + Alipay/WeChat Pay linked to the card for daily spending + a small amount of RMB cash + an optional e-CNY hardware wallet for arrival emergencies. Arrange large surgical or deposit amounts in advance by wire or overseas card.
• Medium- to long-term treatment or rehabilitation (several months or more): on top of the above, open a domestic bank account with your residence permit and link it to mobile payment to eliminate limits and fees.
• Visitors from interconnected Asia-Pacific regions: use your home e-wallet for small offline purchases and reserve the overseas card and cash for larger amounts.
5. Five Pre-Departure Reminders
1. Carry at least two cards from different networks and issuing banks, in case one is blocked by risk control.
2. Ensure you can receive SMS messages in China, to complete real-name verification and one-time codes.
3. After arrival, withdraw a small amount of RMB cash at the airport as a backup.
4. Remember the RMB 200 threshold: QR payments at or below it are free; above it a 3% fee applies.
5. For large medical expenses, confirm arrangements before departure, keep all paperwork, and clarify insurance direct-billing and reimbursement procedures in advance.
Payment should never stand in the way of receiving care with peace of mind. With the right combination of tools, every step, from your first purchase on arrival to settling the final hospital bill, can be smooth and within your control.